Executive summary
For the analyst and the principal, in four lines.
Natural capital is one of the least allocated, most discussed asset categories in institutional finance: under 0.2 percent of institutional portfolios, by one recent survey, despite the underlying systems contributing an estimated 4 to 5 percent of global GDP. The gap is not evidence the category is unproven. It is evidence that most of it has not yet been built to institutional specification. This piece sets out what natural capital is, why allocation has lagged the thesis, and where a single operated permanent-crop orchard actually sits inside that broader category.
What is natural capital, precisely, and why is it hard to allocate to?
Natural capital describes assets whose value derives from a living, biological system rather than from a structure, a contract, or a financial claim alone: farmland, forestry, water rights, and the ecosystem services and credits increasingly built around them. It sits adjacent to infrastructure and real estate in most classification schemes, and resembles neither closely enough to inherit an existing allocation bucket cleanly. That classification ambiguity is not a minor administrative problem, it is reportedly the single largest barrier to scaling institutional allocation. A 2026 analysis citing Preqin (2025) and State Street's Global Market Portfolio (2026) found natural capital represents less than 0.2 percent of institutional capital allocations, despite the underlying natural systems contributing an estimated 4 to 5 percent of global GDP (Climate Asset Management, "Is Natural Capital the New Infrastructure?", August 2026). The report's own framing is specific: asset owners cannot agree where natural capital investment belongs in a portfolio, and that disagreement caps how much capital can flow into it, because the answer determines which internal team, real assets, alternatives, or a dedicated sustainability sleeve, owns the funding decision. A parallel survey of 68 UK institutional asset owners holding more than 3 trillion pounds found 68 percent prioritising well-defined, project-level performance indicators when evaluating strategies in this category, ahead of almost any other criterion. The constraint, in other words, is legible data at the asset level, not investor appetite. There is a demand-side number that puts the gap in scale. As of 2023, an estimated $220 billion dollars a year was directed toward nature-based solutions globally, against roughly $7.3 trillion dollars a year flowing to nature-negative activities; closing that gap is estimated to require nature-positive investment to reach $571 billion dollars annually by 2030. Whatever one makes of the precision of any single figure in that comparison, the order of magnitude is the point: current flows are a rounding error against both the negative activity they are meant to offset and the flow required to meaningfully change that balance.
Is capital actually moving into this category, or is it still theoretical?
It is moving, from a small base, and the growth rate is real even where the absolute numbers remain modest next to institutional portfolios generally. J.P. Morgan Asset Management has rebranded timberland manager Campbell Global as J.P. Morgan Natural Capital. The change reflects the firm's expanding focus on nature-based assets to meet rising institutional demand. Forest Trends and The Nature Conservancy's most recent tracking exercise recorded more than $60 billion dollars in private capital deployed into nature-based investments between 2016 and 2025, across 1,731 transactions, with annual flows increasing roughly fivefold over that period, from an estimated $2.8 billion dollars in 2016 to over $14 billion dollars in 2025 ("Gaining Ground: State of Private Investment in Nature, 2026," June 2026). The same tracking exercise reports over $180 billion dollars in private capital targeted for deployment in the years ahead, drawn from a survey of institutions collectively holding an estimated $207 trillion dollars in assets under management, and finds that 88% of those surveyed report a positive relationship between financial return and environmental or social impact in this category, rather than a trade-off between the two. More than half of the capital tracked went to what the report calls "working landscapes," meaning sustainable agriculture and forestry specifically, rather than to conservation or restoration projects without an operating revenue model. A parallel demand-side indicator sits inside the growth of biodiversity credit markets specifically: a nascent instrument category estimated at $7.1 billion dollars globally in 2025, projected to reach $8.8 billion dollars in 2026 and $38.0 billion dollars by 2033, a compound annual growth rate of 23.3% (Grand View Research, June 2026). That is sector evidence about where institutional and corporate demand for nature-linked instruments is heading generally; it is not a claim that our orchard participates in that market today, and it does not.
Where does farmland specifically sit within natural capital, and how mature is that sub-category?
Further along than most of the rest of the category, and still meaningfully volatile. Nuveen Natural Capital, the largest dedicated farmland manager globally by assets, reported $12.1 billion dollars of farmland assets under management, more than 2 million gross acres, 116 employees and exposure across eight geographies and more than 60 crop types, all as at 31 December 2025, and was ranked the largest farmland manager worldwide by Pensions and Investments as at 30 June 2025. A firm of that scale, staffed at that headcount, is evidence that farmland has been built out to something resembling an operating company, which is the direction the rest of natural capital has not yet travelled as far. But scale of manager is not the same as stability of returns, and the honest current data on that point cuts against the tidy version of the farmland thesis. The NCREIF Farmland Property Index, which reports annual cropland and permanent cropland separately because the two behave differently, showed permanent cropland returning negative 5.43% in 2025 against annual cropland's 3.52%, a gap of roughly 895 basis points, and permanent cropland has now underperformed annual cropland on this index for six consecutive years after nine years in which permanent cropland had led (AgIS Capital, State of Returns, March 2026). This is sector evidence about a different universe of mature, mark-to-market permanent cropland, mostly in the United States, not a claim about this orchard's likely path. But it is directly relevant to the broader natural capital pitch, which sometimes implies that real, biological assets are inherently the calm, uncorrelated allocation. The most current data on the most mature part of the category says otherwise, for now, and a reader should weigh that before accepting the calm-uncorrelated framing at face value.
Where does a single operated orchard sit, specifically, inside this bigger picture?
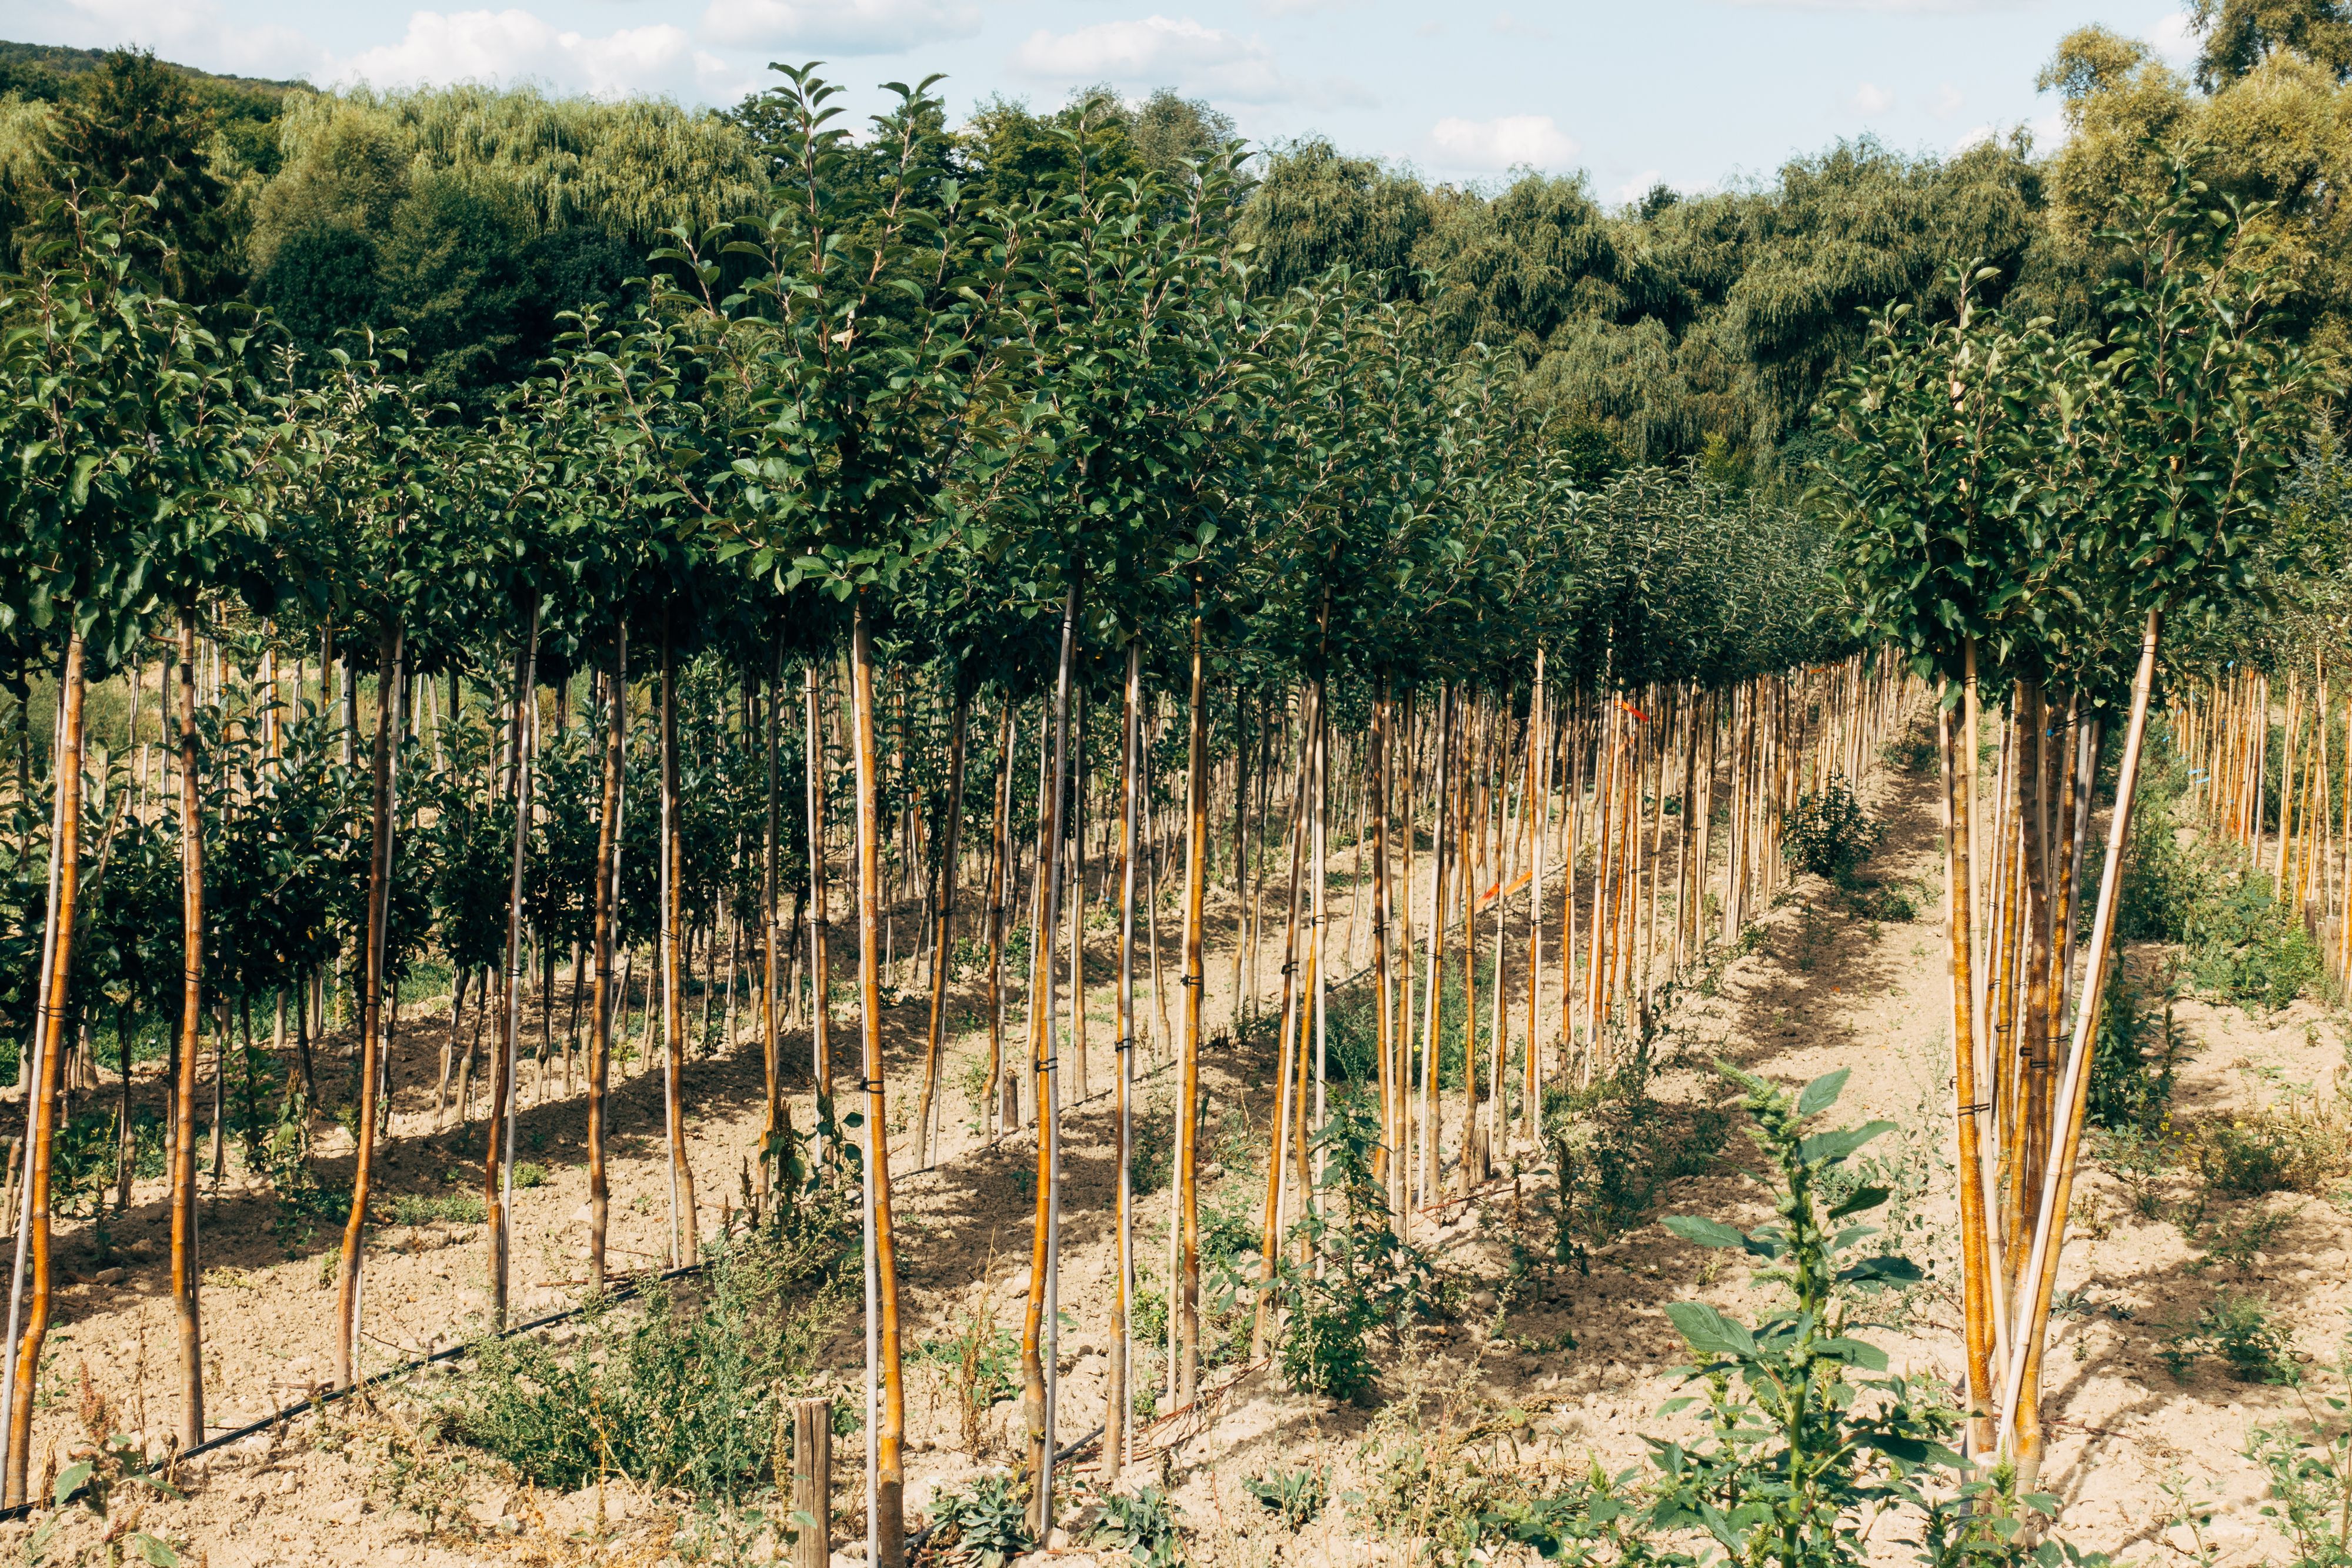
As a narrow, legible answer to the classification problem described above, rather than as an attempt to solve natural capital allocation generally. The structural barrier identified across the sector, repeatedly, is the absence of well-defined, project-level, auditable data: exactly what a diversified natural capital fund, spanning many assets and geographies, finds hardest to publish asset by asset. A single identified orchard inverts that constraint. An investor is not being asked to underwrite a sleeve, a classification, or a fund's aggregate reporting; they are being asked to underwrite one contiguous, mechanised, leased block, at named cadastral lots, with a stated planting schedule, a stated yield curve, and a named agronomy team with comparable operating history elsewhere. That specificity does not remove any of the risks discussed throughout this site: production dependency, the absence of a live secondary market, and total loss of principal chief among them. It does mean the asset does not depend on an allocator first resolving where "natural capital" sits on their model before they can evaluate it; it can be evaluated as a single real-asset cash flow, on its own facts, the way a direct infrastructure or real estate position would be. That is a materially different proposition from buying into the natural capital thesis broadly. It is closer to buying a specific, auditable instance of it, sized as the concentrated single-asset exposure it is, while the category around it continues to build the reporting infrastructure that would let a diversified sleeve be evaluated the same way.
What this doesn't tell you
It does not tell you that natural capital as a category is undervalued, or that current under-allocation represents a market inefficiency waiting to close. The 0.2 percent figure could equally reflect appropriately cautious allocators waiting for better data, rather than an opportunity institutional capital has been slow to recognise. Both readings are consistent with the same number. It does not tell you what this specific orchard will yield, or whether its structure will be repeated at the scale the wider natural capital growth numbers imply.
References
- Treesury sources Treesury Whitepaper STO2 (English certified translation), §3.3.1 p. 22 and §5 p. 41, orchard location, leased area, cadastral identification. Ibid., §1.1.2 pp. 8–9 and §3.3.1 p. 20, Aleksandar Petrović, Chief Agricultural Officer, comparable operating history. Ibid., §7 pp. 51–54, token legal character and structure as a delivery mechanism for this specific asset.
- Sector evidence, not from these orchards Climate Asset Management (2026). "Is Natural Capital the New Infrastructure?" August 2026, citing Preqin (2025) and State Street's Global Market Portfolio (2026); Mallowstreet survey of 68 UK institutional asset owners. Forest Trends and The Nature Conservancy (2026). "Gaining Ground: State of Private Investment in Nature, 2026." Published 22 June 2026. Grand View Research (2026). Biodiversity Credit Market Size, Share and Growth Report, 2026–2033. Published June 2026. Nuveen Natural Capital, Global farmland capabilities. 12.1 billion dollars of farmland assets under management, more than 2 million gross acres, 116 employees, eight geographies and more than 60 crop types, as at 31 December 2025. Ranked number one farmland manager worldwide by Pensions and Investments as at 30 June 2025. AgIS Capital (2026). State of Returns, March 2026. Author: Cody P. Dahl, Ph.D. NCREIF Farmland Property Index, annual vs. permanent cropland returns, 2025.
by Treesury Investment Team